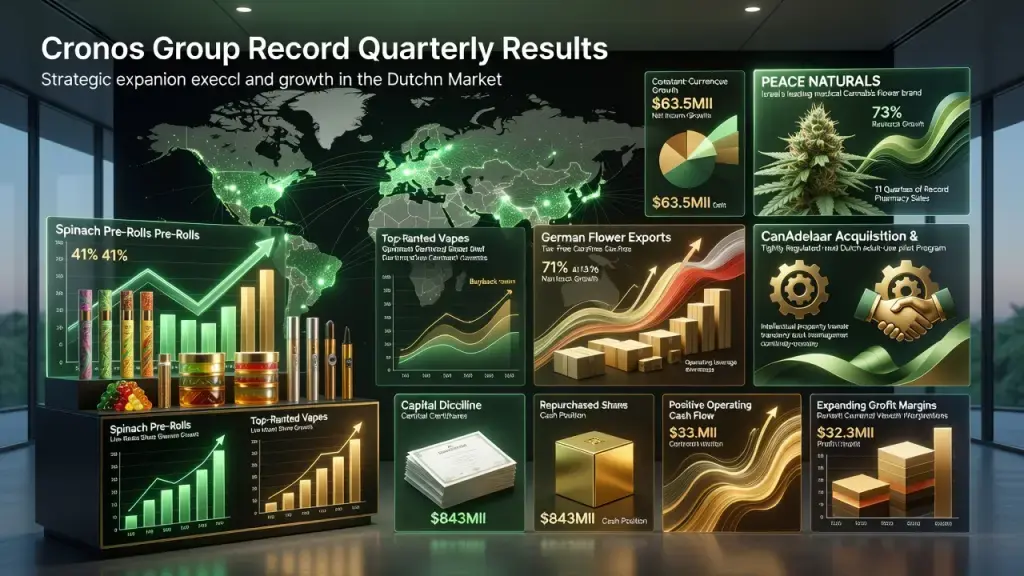
Cronos Group's third-quarter 2026 numbers tell a story that cannabis operators across North America would love to tell about their own books: organic revenue growth, expanding margins, and a shrinking share count, all at once. Net revenue hit $63.5 million, up 73% year-over-year on a constant-currency basis, while gross profit climbed to $32.3 million. For a sector still digesting years of oversupply and compressed wholesale pricing, that combination is notable.
Where the Growth Actually Came From
The mechanics matter here. Cronos attributes much of the gain to a mix shift toward Israel and markets like Germany, where cannabis flower sales carry no excise taxes - a structural advantage that doesn't exist for most Canadian or U.S. operators squeezed by provincial markups or, south of the border, Section 280E. Higher sales volumes also spread fixed overhead across a larger base, the kind of operating leverage that licensed producers have chased since legalization but rarely achieved consistently. In Canada, Spinach® grew retail sales 41% year-over-year against a flat national market - a share gain, not just a rising tide. The brand held the #1 position in vapes for a third straight quarter and in edibles for a ninth, built on a renovated pre-roll lineup and new product launches, including a live-resin-infused gummy line.
Israel and the International Flower Trade
Eleven consecutive quarters of record revenue in Israel is the kind of streak that deserves scrutiny rather than applause alone. PEACE NATURALS® remains the top medical cannabis brand there, per pharmacy data Cronos itself collects - useful context, though it's worth remembering that's a company-reported metric, not an independent audit. More interesting is the 614% year-over-year jump in international revenue outside Israel, concentrated in German flower demand. That kind of growth off a small base is easy to produce and hard to sustain; the real test will be whether cultivation capacity and genetic breeding programs can keep pace as European medical and adult-use frameworks mature.
The CanAdelaar Deal and What It Signals
Closing the CanAdelaar acquisition in October, after the quarter ended, gives Cronos a foothold in the Netherlands' regulated adult-use pilot program - one of the more tightly controlled experiments in cannabis retail anywhere in the world. Integration, including intellectual property transfer, is underway, with the former CEO staying on as general manager. For operators watching Europe, this is a reminder that market entry there still runs through narrow regulatory pilots, not open licensing, and that scale requires patient capital and local operational know-how, not just a balance sheet.
Capital Discipline Amid Growth
Cronos repurchased 15.5 million shares for $42.3 million through nine months, continuing a buyback program the company frames as an efficient use of capital given its cash position of roughly $843 million. Positive operating cash flow for three consecutive quarters gives it room to fund acquisitions and repurchases simultaneously - a flexibility most cannabis multi-state operators, still managing debt loads and 280E tax burdens, simply don't have. Net income actually declined year-over-year, to $17.8 million from $28.3 million, driven by a tax provision replacing a prior-year benefit and higher operating costs tied to sales, marketing, and litigation matters. The gross profit story is strong; the net income line is a reminder that top-line records don't always translate cleanly to the bottom.